
EU/ITA - In the euro area, the macroeconomic outlook continues to show mixed signals, but overall, consistent with the most recent surveys, they indicate that the economy remained expanding in December and that the economic situation is relatively favorable overall. Growth is expected to average 1.2% in 2026 and 1.4% in 2027 and 2028.
In December, actual inflation fell to 2%, a slight decline from 2.1% in November, and the ECB highlighted that its statutory target had been achieved. Core inflation also shows signs of cooling, standing at 2.3%. The main source of price pressure comes from services. Inflation in this sector rose from 3.5% to 3.4%, a level that continues to be closely monitored, also due to continued sustained wage growth.
The labor market remains a supporting factor, confirming the resilience of employment despite the economic slowdown. Unemployment expectations are improving, with the rate expected to decline to 10.9% from 11%, while the actual figure for November stood at 6.3%, very close to the all-time low of 6.2%. Consumption also shows mixed trends. On a quarterly basis, retail trade volumes decreased by 0.2% for food, beverages, and tobacco, while they increased by 0.4% for non-food products excluding fuel, and by 0.1% for motor fuel. On a year-on-year basis, however, the picture appears more solid: retail sales increased by 1.1% for food, beverages, and tobacco, by 3.5% for non-food products, and by 1.1% for fuel.
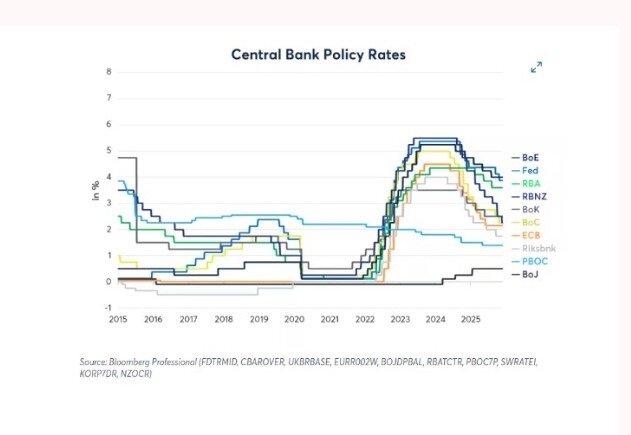
On the real estate front, expectations point to a 3.4% increase in house prices, while on the credit front, a slight easing of mortgage rates is expected. Against this backdrop, the ECB continues to exercise extreme moderation, both in its tone and its decisions. Interest rates, unchanged since June 2025 (see image below), remain unchanged, likely for the entire 2026 term, with the potential for a small cut in the event of a further deflationary downturn. Persistent pressures in services and uncertainties about growth suggest that any decision will need to be calibrated with extreme caution. These signs point to a more balanced environment, albeit lacking real momentum.
EU/ITA - Nell’area euro il quadro macroeconomico continua a mostrare segnali contrastanti, ma nel complesso coerenti con le indagini più recenti indicano che l’economia è rimasta in espansione a dicembre e che la situazione congiunturale è nel complesso relativamente favorevole. La crescita dovrebbe attestarsi in media all'1,2% nel 2026 e all'1,4% nel 2027 e nel 2028.
In un quadro di progressiva normalizzazione, le aspettative di inflazione dei consumatori restano sostanzialmente stabili a novembre: al 2,8% a dodici mesi, al 2,5% a tre anni e al 2,2% a cinque anni. A dicembre l’inflazione effettiva è scesa al 2%, registrando una lieve flessione rispetto al 2,1% di novembre e la BCE ha evidenziato come sia stato raggiunto l'obiettivo target del suo statuto. Anche l’inflazione core mostra segnali di raffreddamento, attestandosi al 2,3%. La principale fonte di pressione sui prezzi deriva dai servizi. L’inflazione del comparto, passata dal 3,5% al 3,4%, un livello che continua ad essere vigilato con attenzione, anche a causa della dinamica salariale ancora sostenuta.
Il mercato del lavoro resta un elemento di sostegno in una dinamica che conferma la tenuta dell’occupazione, nonostante il rallentamento dell’economia. Le aspettative sulla disoccupazione migliorano, con un tasso atteso in calo al 10,9% dall’11%, mentre il dato effettivo di novembre si è attestato al 6,3%, molto vicino al minimo storico del 6,2%. Anche i consumi mostrano andamenti differenziati. Su base congiunturale, il volume del commercio al dettaglio diminuisce dello 0,2% per i prodotti alimentari, bevande e tabacco, mentre cresce dello 0,4% per i prodotti non alimentari, esclusi i carburanti, e cala dello 0,1% per i carburanti per autotrazione. Su base tendenziale, però, il quadro appare più solido: le vendite al dettaglio aumentano dell’1,1% per alimentari, bevande e tabacco, del 3,5% per i prodotti non alimentari e dell’1,1% per i carburanti.
Sul fronte immobiliare, le aspettative indicano un aumento dei prezzi delle case del 3,4%, mentre sul fronte del credito si intravede un lieve allentamento sui tassi dei mutui. In questo scenario, la BCE continua a muoversi con estrema moderazione sia nei toni che nelle decisioni. Sui tassi di interesse, invariati da giugno 2025 (si veda grafico in alto), l’orientamento resta quello di uno status quo prolungato, verosimilmente per tutto il 2026, salvo considerare un taglio di piccola entità nel caso di ulteriore flessione deflazionistica. Le persistenti pressioni nei servizi e le incertezze sulla crescita suggeriscono che ogni decisione dovrà essere calibrata con estrema cautela. Segnali che contribuiscono a delineare un contesto di maggiore equilibrio, pur senza un vero e proprio slancio.
Analisti associati @euroeconomie.it*
* This contribution is not a journalistic article but an analytical brief - Questo contributo non è un articolo giornalistico ma un brief analitico